The Power of Bidding
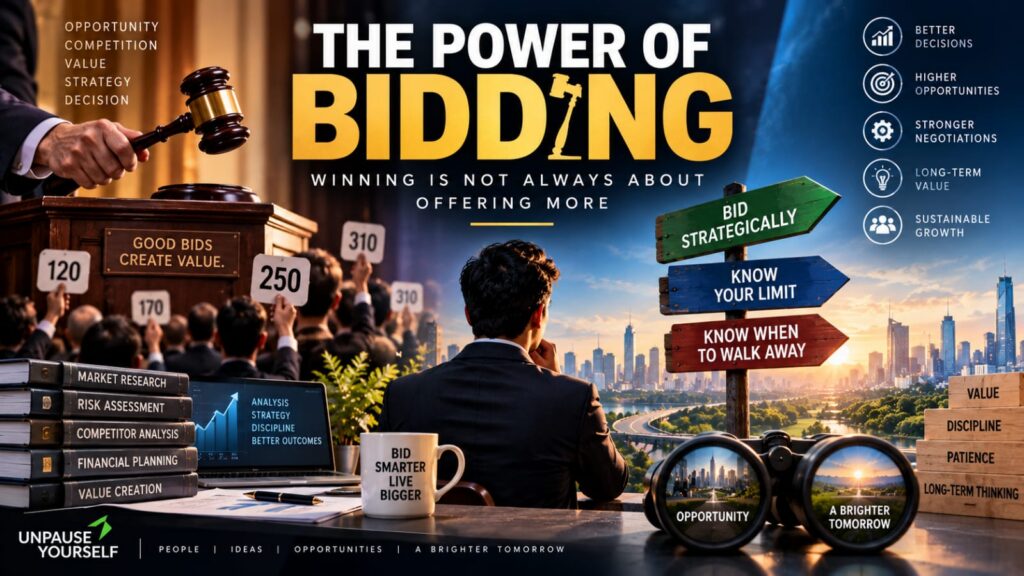
Winning Is Not Always About Offering More
Every bid tells a story. It reveals what you value, how much risk you understand, how well you know the competition and whether you have the discipline to walk away.
We often associate bidding with auctions.
Someone makes an offer. Another person raises it. Competition intensifies. Eventually, the highest bidder wins.
But bidding is much bigger than an auction room.
Businesses bid for contracts. Companies compete for government tenders. Agencies pitch for clients. Investors bid for assets. Freelancers compete for projects. Buyers negotiate for property. Startups compete for talent and capital.
And, metaphorically, we bid throughout our careers with our time, attention, reputation, money and effort.
The fascinating part is that the most powerful bidder is not necessarily the one willing to offer the most.
Very often, it is the one who understands value better than everyone else.
A Bid Is More Than a Price
Suppose an asset is being auctioned.
One participant sees it and thinks:
“How much do I need to offer to win?”
Another asks:
“What is this actually worth to me?”
Those questions sound similar.
They are fundamentally different.
The first person is focused on defeating competitors.
The second is focused on making a good decision.
That distinction lies at the heart of intelligent bidding.
A bid should represent the intersection of three things:
Value. Opportunity. Discipline.
Remove value, and you may overpay.
Remove opportunity, and you may bid on something that offers little strategic benefit.
Remove discipline, and competition can take control of your judgement.
Why Competition Changes Our Thinking
Imagine you want to purchase something worth approximately ₹10 lakh to you.
You decide beforehand that ₹10 lakh is your absolute limit.
The bidding begins.
₹8 lakh.
₹8.5 lakh.
₹9 lakh.
Then someone offers ₹9.5 lakh.
You respond with ₹9.75 lakh.
They offer ₹10 lakh.
Now something psychological happens.
You are no longer simply evaluating the asset.
You are thinking:
“I have already come this far. I can’t lose it now.”
So you offer ₹10.25 lakh.
Then ₹10.5 lakh.
Soon, the objective has quietly changed.
You are no longer trying to acquire something at an attractive value.
You are trying to win.
And winning at any price can become another form of losing.
The Winner’s Curse
Economics and auction theory contain an important concept known as the winner’s curse.
It can arise particularly when bidders are uncertain about an item’s underlying value.
Imagine several companies bidding for an asset whose true economic value is difficult to determine.
Some estimates will naturally be conservative.
Others will be optimistic.
The bidder with the most optimistic valuation may therefore submit the highest bid—and win.
But that creates an uncomfortable possibility:
What if you won precisely because you overestimated the value?
This principle extends far beyond traditional auctions.
A company can overpay for an acquisition.
A business can quote an unsustainably low price simply to secure a contract.
A property buyer can become emotionally attached and exceed a sensible valuation.
A freelancer can underprice services to defeat competitors.
In every case, winning the transaction does not automatically mean winning economically.
Sometimes the Best Bid Is No Bid
One of the most underrated capabilities in business is the ability to walk away.
People naturally celebrate deals that happen.
We rarely celebrate the deals someone intelligently rejected.
Yet disciplined decision-makers understand that every opportunity has a threshold.
Beyond that threshold, the economics stop making sense.
Imagine a company bidding for a prestigious contract.
Winning would create headlines and visibility.
But careful analysis shows that delivering the project at the required price would consume enormous resources, create operational risk and generate almost no profit.
Should the company still pursue it simply because the contract is prestigious?
Not necessarily.
Sometimes:
“We will not bid at these terms”
is a stronger business decision than:
“We won the contract.”
The objective of bidding is not to win everything.
It is to win the right opportunities at the right terms.
Preparation Creates Bidding Power
Powerful bidding often begins long before the first offer is made.
The sophisticated bidder studies:
- the underlying value,
- market conditions,
- competing alternatives,
- likely competitors,
- financial capacity,
- risks,
- opportunity costs,
- negotiation leverage,
- and the point at which walking away becomes rational.
This creates something invaluable:
A predetermined boundary.
When the pressure of competition begins, that boundary protects judgement from emotion.
In other words, one of the smartest decisions in bidding is often made before bidding starts.
Price Is Not Always the Only Bid
This becomes particularly important in business.
Suppose three companies are competing for a contract.
Company A offers the lowest price.
Company B offers a slightly higher price but significantly better execution capability.
Company C offers expertise, stronger support, faster delivery and lower long-term risk.
Which is the strongest bid?
There is no universal answer.
It depends on what the buyer values.
That is precisely the point.
Bidding is not always about price. It is about the complete value proposition.
Reliability can be part of a bid.
Experience can be part of a bid.
Speed can be part of a bid.
Trust can be part of a bid.
Quality can be part of a bid.
Reputation can be part of a bid.
A powerful bidder understands what the other side is actually trying to achieve.
The Lowest Bid Can Be Expensive
This principle deserves particular attention.
The cheapest proposal is not automatically the most economical proposal.
Imagine hiring a contractor for ₹8 lakh instead of another quoting ₹10 lakh.
The ₹8 lakh contractor looks cheaper.
But if delays, poor workmanship and corrections eventually cost another ₹4 lakh, the supposedly cheaper decision becomes a ₹12 lakh problem.
Price is visible immediately.
Cost is sometimes revealed later.
Sophisticated procurement therefore evaluates more than the initial number.
It considers quality, reliability, execution, lifecycle cost and risk.
Bidding Is Also About Information
Every bid communicates information.
If competitors aggressively pursue an asset, you may infer that they perceive value in it.
If nobody bids, that also tells you something.
If a buyer repeatedly rejects offers around a certain price, you begin understanding expectations.
If a competitor suddenly withdraws, there may be information you do not possess.
But this creates another danger.
Never assume that other bidders know more than you.
Competition can create artificial confidence:
«“If everyone wants it, it must be valuable.”»
History repeatedly demonstrates that crowds can overestimate value together.
Intelligent bidding therefore requires an unusual balance:
Observe the market without surrendering your judgement to it.
The Invisible Bid We Make Every Day
There is another way to understand bidding.
Every person possesses limited resources:
Time.
Energy.
Attention.
Money.
Reputation.
Every opportunity asks us to allocate some combination of them.
In that sense, life itself contains bids.
When you spend three years building a company, you are bidding your time on its future.
When you pursue a qualification, you are bidding effort on future capability.
When you build a professional relationship, you invest attention and trust.
When you accept one opportunity, you may implicitly decline another.
This is called opportunity cost.
Every “yes” contains an invisible “no” somewhere else.
That makes resource allocation one of the most consequential forms of bidding.
Never Bid Your Identity
Competition becomes dangerous when outcomes become connected to ego.
“I must win this deal.”
“I cannot let that person beat me.”
“I have already invested too much to stop.”
These statements shift decision-making away from economics and towards identity.
The disciplined bidder can separate the two.
Losing an auction does not make you unsuccessful.
Walking away from a negotiation does not make you weak.
Declining an opportunity does not mean you lacked ambition.
Sometimes walking away simply means:
The numbers stopped making sense.
That is discipline—not defeat.
Know What You Are Bidding For
Before making any significant bid—financial, professional or entrepreneurial—five questions are worth asking:
What is this genuinely worth to me?
What am I risking to obtain it?
What alternatives do I have?
At what point does the opportunity stop making sense?
Am I still pursuing value—or am I now pursuing victory?
The fifth question may be the most important.
Because competition has a remarkable ability to turn rational people into emotional decision-makers.
The Unpause Perspective
At Unpause Yourself, we believe opportunities matter—but judgement matters more.
The modern world constantly invites us to bid.
For contracts.
For investments.
For businesses.
For jobs.
For attention.
For opportunities.
Sometimes even for recognition.
But progress does not come from winning every competition.
It comes from understanding which competitions deserve your resources in the first place.
Bid boldly when the value is clear.
Prepare before entering.
Understand the downside.
Know your limits.
Compete on value rather than ego.
And never become so emotionally invested in winning that you forget why you entered.
Because ultimately:
The power of bidding is not knowing how high to go.
It is knowing exactly where to stop.
Winning feels powerful.
But occasionally, the person who walks away has made the strongest bid of all.
About The Author